If you have been tracking Indian equity markets over the past few years, you know the domestic growth story has been phenomenal. But as any seasoned investor will tell you, true portfolio resilience comes from global diversification.
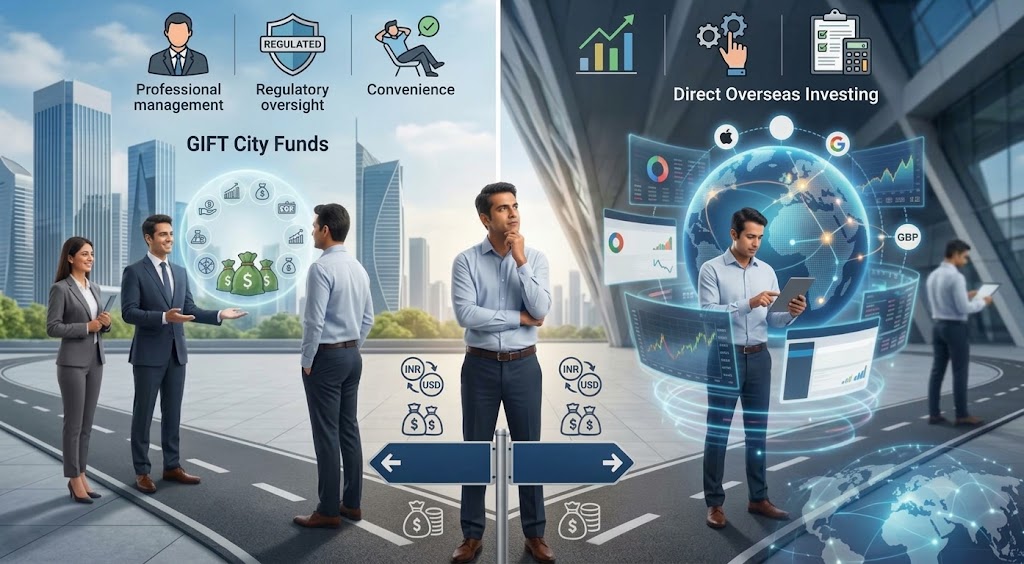
Whether you want to own a piece of tech giants like Apple and Nvidia or gain broad exposure to S&P 500 ETFs, Indian investors today have two major gateways: GIFT City Funds and Direct Overseas Broking Accounts.
While both fall under the Reserve Bank of India’s Liberalised Remittance Scheme (LRS) limit of $250,000 per financial year, they offer drastically different experiences in terms of control, tax friction, and upfront costs.
Today, let’s break down these two paths, unpack the notorious 20% TCS trap, and look at how top wealth managers—like Shweta Rajani from Anand Rathi Wealth—suggest structuring your international portfolio.
The Core Split: Convenience vs. Direct Control
Before diving into numbers, ask yourself one question: Do you want to be a hands-on stock picker, or do you prefer passive, hassle-free asset allocation?
GIFT City Funds (IFSCA Regulated)
Think of this as a hassle-free bridge. These funds pool capital under the International Financial Services Centres Authority (IFSCA) framework. You get daily NAV tracking, quarterly portfolio disclosures, and professional fund management. You don’t have to worry about execution or overseas tax filings—the fund house handles everything.
Direct Overseas Investing
You open an account with an international brokerage (like Vested, Interactive Brokers, or Charles Schwab) and directly buy US stocks or global ETFs. You get total control over stock selection, entry/exit timing, and sector allocation. The catch? You are personally responsible for corporate action tracking, currency conversions, and complex cross-border tax compliance.
The Hidden Friction: Costs & The 20% TCS Factor
Fees can silently eat away at your long-term compound returns. Here is how the cost structures differ:
Cost Structure Breakdown
- GIFT City Funds: You pay an ongoing Expense Ratio (management and operational fees) plus potential exit loads.
- Direct Investing: You bypass fund management fees, but you incur brokerage commissions, platform maintenance fees, wire transfer charges (FX markup), and currency conversion fees.
The 20% TCS Real-World Reality Check
Under LRS regulations, any remittance abroad exceeding ₹10 Lakhs in a financial year (excluding medical and education purposes) attracts a 20% Tax Collected at Source (TCS).
If you decide to remit ₹50 Lakhs abroad to invest in US equities, you will need to pay an additional ₹8 Lakhs upfront as TCS.
It’s crucial to remember that TCS is not an extra expense or tax—it is a tax advance that you can claim back or offset against your annual income tax liability when filing your ITR. However, it locks up your liquidity for months. If you are cash-flow tight, factor this 20% cash lockup into your capital planning!
Tax Nuances: Foreign Capital Gains & Dividend Withholding
Navigating foreign taxation requires extra attention to avoid nasty surprises at tax time:
Capital Gains
For foreign shares held directly, short-term gains (held ≤ 24 months) are added to your income and taxed at your applicable slab rate. Long-term gains (held > 24 months) are taxed at 12.5% without indexation. (Note: The ₹1.25 Lakh tax-free threshold available on certain Indian equities DOES NOT apply to foreign stock gains).
Dividend Taxes
Dividends earned from US stocks are taxed at your marginal slab rate in India. Furthermore, the US IRS typically deducts a 25% withholding tax at source before the money even hits your account. You can claim credit for this foreign tax paid under the Double Tax Avoidance Agreement (DTAA) by filing Form 67, but it adds administrative friction.
GIFT City Tax Wrapper
The taxation is wrapped within the fund structure itself, with net gains reflecting directly in the NAV.
How Much Global Exposure Do You Really Need?
A common mistake retail investors make is going “all in” on global markets after a big US tech rally, or completely avoiding international assets out of fear of tax complexity.
Portfolio Allocation Benchmark
According to wealth managers, if your total investment portfolio exceeds ₹5 Crores, a reasonable allocation to international assets sits between 5% to 10%.
For instance, on a ₹10 Crore portfolio, allocating ₹50 Lakhs to ₹1 Crore into global assets (e.g., S&P 500 ETFs, global mega-cap tech) provides meaningful geographic diversification without over-complicating your tax life.
The Domestic Anchor
Global investing should supplement your domestic portfolio, not replace it. India remains one of the world’s fastest-growing major economies. Keep your core equity exposure anchored in well-diversified domestic mutual funds (across flexi-cap, mid-cap, and large-cap categories), and use international investments as a hedge against rupee depreciation and single-country concentration risk.
Final Verdict: Which Route Should You Pick?
Choose GIFT City Funds If:
You value peace of mind, want hassle-free tax management, and prefer professional fund managers to navigate asset allocation for you.
Choose Direct Overseas Investing If:
You are an experienced investor who wants to buy specific stocks (like Tesla, Nvidia, or Microsoft), build custom ETF baskets, and don’t mind handling tax filings like Form 67 and foreign asset disclosures.
What about you? Are you currently investing in global markets or sticking strictly to Indian equities? Let me know your thoughts in the comments below!